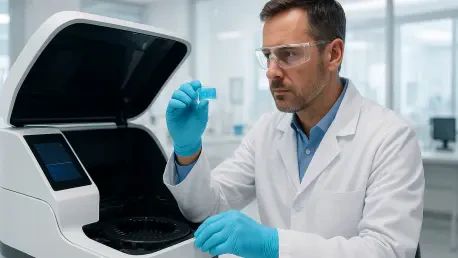
The global market for in-vitro inflammatory bowel disease diagnostics is projected to climb to USD 2.9 billion by 2034 as healthcare providers shift toward non-invasive protocols. This movement reflects a broader transformation within the gastrointestinal sector, where the focus is intensifying on early detection and chronic management of Crohn’s disease and ulcerative colitis. These conditions often present a labyrinth of symptoms that overlap with other digestive ailments, creating a high demand for precise laboratory tools. By utilizing biological samples such as stool, blood, and genetic material, in-vitro diagnostics offer a window into the body’s inflammatory state without the immediate need for surgical intervention. This evolution is vital given the complexities of patient care in the 2026 clinical environment, where healthcare systems are striving to improve efficiency. The steady financial growth from 2026 to 2034 underscores the critical role these tests play in modern medicine and patient management.
Core Drivers of Industry Growth
One of the most significant factors fueling this market expansion is the rising global incidence of inflammatory bowel conditions, which is no longer confined to traditionally high-prevalence Western nations. As urbanization accelerates and dietary habits change in emerging economies, clinicians are seeing a surge in new cases that require rapid and accurate screening. Historically, the medical community relied on “gold standard” invasive procedures like endoscopies and colonoscopies, but there is now a palpable push for stool and blood-based alternatives. These non-invasive protocols allow practitioners to differentiate between various inflammatory states with significantly less physical strain on the patient. This transition not only improves the overall patient experience but also provides a more cost-effective method for long-term monitoring. By reducing the frequency of hospital-based invasive check-ups, healthcare providers can reallocate resources while maintaining a high diagnostic standard.
Beyond patient comfort, the integration of sophisticated technology like Artificial Intelligence and Machine Learning is accelerating market growth. These digital tools allow for the processing of complex data sets, enabling doctors to predict disease flares before they become symptomatic. In the context of personalized medicine, diagnostic tests are now being used to quantify the “inflammatory load” of a patient, which is essential for optimizing the dosage of expensive biologic and immunosuppressant therapies. This precision ensures that treatments are tailored to the individual’s specific biological response, rather than following a generic one-size-fits-all approach. As we progress from 2026 toward the end of the decade, the synergy between advanced diagnostics and targeted therapeutics is expected to become the cornerstone of care. This data-driven strategy not only enhances clinical outcomes but also mitigates financial risks for healthcare systems prioritizing results over traditional practices.
Segmentation and Technological Innovation
The technological landscape of the IBD market is primarily defined by a diverse array of specialized assays and testing modalities designed for high accuracy. Key biomarkers, such as fecal Calprotectin and Lactoferrin, have emerged as indispensable tools for distinguishing chronic inflammation from non-inflammatory conditions like Irritable Bowel Syndrome. These markers allow clinicians to assess the state of the intestinal mucosa directly through biological samples, providing a level of detail that was previously difficult to achieve without direct visualization. Furthermore, the development of high-throughput automated analyzers has enabled laboratories to process large volumes of tests with minimal turnaround times. This industrialization of diagnostic testing is critical for meeting the needs of a growing patient population while maintaining rigorous quality control. By standardizing these biological assessments, the medical community can ensure that patients receive consistent care regardless of location.
Innovation is also moving toward the decentralization of testing through Point-of-Care (POC) solutions and smartphone-integrated technologies. These rapid test kits are designed for use in outpatient settings or even at home, providing immediate feedback that can guide treatment adjustments in real-time. By utilizing optical readers on mobile devices, the margin for human error in interpreting test results is significantly reduced, as AI-driven algorithms provide objective quantification of inflammatory markers. Another vital trend is the rise of companion diagnostics, where diagnostic firms collaborate with pharmaceutical giants to monitor patient responses during clinical drug trials. This approach ensures that new therapies are validated alongside the tools needed to measure their success, creating a more integrated ecosystem for drug development. As these POC tools become more sophisticated from 2026 to 2034, they will likely redefine the patient journey, moving diagnostic power from labs directly to clinicians.
Navigating Challenges and Future Regional Opportunities
Despite the optimistic outlook, the industry must still contend with several logistical and clinical hurdles that could temper the pace of adoption. Diagnostic ambiguity remains a persistent challenge, as biomarker levels can occasionally overlap between different conditions, necessitating confirmatory imaging or histology in complex cases. Moreover, the implementation of specialized tests is frequently hindered by inconsistent insurance coverage and significant variations in healthcare policy across international borders. These reimbursement disparities mean that even the most advanced diagnostic tools may remain inaccessible to patients in regions with less developed insurance frameworks. Addressing these gaps requires a concerted effort from manufacturers to demonstrate the long-term cost-effectiveness of their products to policymakers. Until standardized reimbursement protocols are established globally, the full potential of these innovations may not be realized in every market, potentially widening the health equity gap.
The path forward for the IBD diagnostics sector involved a strategic focus on expanding laboratory infrastructure in high-growth regions such as the Asia-Pacific and Latin America. Manufacturers recognized that the mature markets of North America and Europe reached a level of saturation that necessitated looking toward emerging economies for continued expansion. This shift required significant investment in localized distribution networks and the adaptation of technology to meet regional regulatory requirements. By prioritizing the integration of digital health tools with traditional laboratory assays, industry leaders successfully created a more resilient and accessible diagnostic framework. These efforts paved the way for a more proactive approach to gastrointestinal health, where early intervention became the standard rather than the exception. Ultimately, the industry moved toward a model that valued long-term patient outcomes, ensuring that the transition to precision-based protocols delivered tangible benefits.